
The Money crunch in the system has made insurance and mutual fund companies to formulate more and more innovative products.
Today (16 Feb. 09) LIC (Life Insurance Corporation of India) has launched its new scheme named “Jeevan Varsha” which offers guaranteed return with survival benefit. This plan is launched keeping the success of “Jeevan Aastha “. This money back plan will be available from 16 Feb. 09 to 31 Mar. 09. The term of this policy would be 9 (Nine) and 12 (Twelve) years respectively. One of the most important plus point in this plan in the survival benefit which will give return after every 3 (Three years) which in return will create higher rate of return.
Lets workout “Jeevan Aastha “ in reality,
The Life Insurance Corporation’s (LIC’s) Jeevan Aastha, Religare Aegon’s Life Guaranteed Return Plan and IDBI Fortis’ Bondsurance are some to have hit the market recently.
LIC’s Jeevan Aastha has got the most attention because it has offered 9 percent (Rs 90 per Rs 1,000) and 10 percent (Rs 100 per Rs 1,000) returns for a period of 5 years and 10 years, respectively. “Some investors were in such frenzy that they withdrew from bank fixed deposits to invest in these products,
However, there is a catch in LIC’s return calculations. While other companies have clearly stated that they would give a compounded rate of interest, LIC Jeevan Aastha’s advertisements have put it in rupee terms. What the insurer has not said is that the returns will be based on simple interest.
Let’s look at how this product will work. Jeevan Aastha offers Rs 100 and Rs 90 per Rs 1,000 invested for 10 and 5 years respectively. If a person aged 35 wants a cover of Rs 3 lakh for five years, the one-time premium is Rs 51,930. On death, the family stands to get Rs 3 lakh in the first year. The guaranteed death benefit falls from Rs 3 lakh to Rs 1.09 lakh in the second year and rises marginally to Rs 1.22 lakh in the fifth year.
On survival, the maturity value will be Rs 72,500. So, in effect, the policy-holder makes Rs 20,570 on a premium of Rs 51,930. That means the compounded rate of return is a mere 6.73 percent.For a person, who is 60 years old, the one-time premium is Rs 57,045 and the maturity value is same at Rs 72,500. That effectively works out to 4.83 percent compounded interest.
Compare this with a bank fixed deposit and the numbers are much more impressive. An investment of Rs 51,930 for five year at the rate of 9 percent would give returns of Rs 81,037. That is, Rs 29,107 (Rs 8,537 more than Jeevan Aastha). It’s simply because the interest is compounded. .
From an investment perspective, returns are quite low. Returns of 6-odd percent is worse than what any bank fixed deposit offers. Even Public Provident Fund offers a substantially higher rate at 8 percent.
I have done a mistake with Jeevan Aastha , Not now with Jeevan Varsha again. My learning to this is "Don't mix Insurance and investment".
“Investors need to calculate returns from a product properly before putting in their money,”


Its been long time that I did not thought on Investment and insurance option. Want to make profit out Of Satyam Shares Investment Loss. Everybody is aware of recent Satyam fiasco. I got badly stung and I would like to share my experience so that others can avoid making similar mistakes.
The day Ramalingam Raju resigned, I saw the share price of Satyam tumble from Rs 180 to Rs 90 in a matter of minutes. Now that by itself cannot be a valid reason for the share price to tumble. I became greedy and bought 2000 shares of Satyam @ Rs 90.
Later on in the same day, I learnt that he confessed to committing a series of frauds !!! Now that is something serious. If the profits had been manipulated to the extent of Rs 7,000 Crores over several years, then the real value of the Satyam share should be Rs 10.
Justifiably, the share price of Satyam fell to Rs 10 (or actually to Rs 6.50 also) the very next day and is fluctuating between Rs 20 to Rs 38.
I lost a great deal of mooney in the process. How does one come out of the messy siutation?
The only solution is to sell some shares of Satyam at every rise and buy them back at a lower price. Even if I sell 500 shares every day and buy back at a profit of Rs 2 after deducting all expenses, I make a profit of Rs 1,000 per day. I may not be lucky enough to do it every day so it may take a year to come out of the mess.
The moral of the story: Do not buy shares of any Company based on partial news. Do a complete due diligence and then invest wisely.
Pension Plans. This is a very important aspect of Financial Planning. There is no point in slogging throughout life and retiring like a pauper. You must be prepared to make a few sacrifices during the working years to save as much as you can to create a healthy corpus for retirement. You must also invest it wisely to ensure proper growth and benefits.
Till a few years ago, investment of up to Rs 10,000 made under Section 80CCC could reduce your taxable income by the amount invested. But only one-third of the maturity amount was tax free and the remaining two-third was taxable. It was a good option then; but not now. Section 80CCC has been merged with Section 80C. So if you have already taken any Pension Plan earlier, please see if there is an exit route.
A very interesting development is that you can seek to provide for your retirement pension through a "Reverse Mortgage" of your existing home / flat. You can pledge your property to a Bank and they will give you some money every month. Your children have the option of repaying all the amounts taken by you along with interest to the Bank if they wish to take possession of the property after your demise. If they refuse to do so, the Bank will sell the property to recover their dues. They may give the balance (if any) to your nominee.
A good ULIP may prove to be the best Pension plan for the following reasons:
1. Withdrawals are tax free while we a still in the EEE Regime where all the three phases of the investment cycle (Investment, growth and withdrawals) are exempt from tax.
2. Withdrawals will remain free even when EET is implements with prospective effect. Withdrawals from plans started before the cut off date will remain tax free; but withdrawals from plans started after the cut off date will be taxed. Some good ULIPs run through till age 99. Having started the plan before the cut off date, you can enjoy tax free returns till age 99. Besides, you can benefit from frequent Switching as explained during my presentation by investing in a ULIP. If you try to practice Switching in ELSS or any other investment, you may have to pay the exit load, 15% short term Capital Gains and Entry load. Besides, withdrawal from the new plan will be taxed as investment is being made after the cut off date.
To save tax under Section 80C investment in any of the following qualify:
1. NSC
2. PPF
3. ELSS
4. ULIP
5. Principle repayment of Home loan
You can reduce your taxable income by Rs 1 lakh by investing in any of the above Schemes.
NSC is the worst option as you get 8% return which is taxable. If you are in the 30% tax bracket, the effective post tax return works out to 5.6% which may not even beat inflation.
PPF is slightly better as it offers 8% tax free returns and you may get 1 or 2 % growth net of inflation.
ELSS is a better option as you may get a better return assuming Share Markets grow @ 17% CAGR. But there is a lock in period for 3 years. You cannot sell / switch in the first 3 years. You will remain a silent spectator watching your fund values erode in a falling market.
A Good ULIP is much better
talk to the master for more details at http://fitnessfundas.
A Ponzi scheme is a fraudulent investment operation that involves promising or paying abnormally high returns ("profits") to investors out of the money paid in by subsequent investors, rather than from net revenues generated by any real business. It is named after Charles Ponzi, His aliases include Charles Ponei, Charles P. Bianchi, Carl and Carlo.
In December 2008, former chairman of the NASDAQ Stock Market, Bernard Madoff, was arrested and charged with a single count of securities fraud, but one which "may rank among the biggest frauds ever" totaling "$50 billion of fraudulent loses."
A Ponzi scheme has similarities with a pyramid scheme though the two types of fraud are different.

What is The Ponzi scheme?
an idea which others would later, independently, invent as the Yellow Pages. Ponzi, unfortunately, was unable to sell this idea to businesses, and his company failed soon after.
A few weeks later Ponzi received a letter in the mail from a company in Spain asking about the catalog. Inside the envelope was an international postal reply coupon (IRC), something which he had never seen before. He asked about it and found a weakness in the system which would in principle allow him to make money.
Ponzi canvassed friends and associates to back his scheme, offering a 50% return on investment in 45 days. The great returns available from postal reply coupons, he explained to them, made such incredible profits easy. He started his own company, the Securities Exchange Company, to promote the scheme.
Some people invested, and were paid off as promised. The word spread, and investment came in at an ever-increasing rate. Ponzi hired agents and paid them generous commissions for every dollar they brought in. By February 1920, Ponzi's total take was US$5,000, a large sum for the time.
Its been long time That I did not do any search on or about insurance and investment, here is one aboutGold Is Fast Emerging As The Safest Asset To Invest Many times wonder with news of recession, attacks by sick people and all. But for a common man like me; its hard hitting by recession as have put some money in Stock when the stock market was at its peak level, Well I did not follow warren buffet that time, but now I am following his mantra's.
Here is one more digg for your hard earn money to park.
Gold has historically been an excellent hedge against inflation.
Why Gold is safest asset to invest?
The social and psychological repercussions of the Mumbai terror attack, lasting three long days is far reaching. The jewelers were dealing with a situation of lower demand and this has only further compounded the losses.
But on the other hand, gold is fast emerging as the safest asset to hold during the current troubled times. Despite the terror attacks, gold prices in the local market have not been impacted. Prices have not been influenced by the attacks as the metal usually shows a downward movement only when faced with larger international crises and possible disruptions to oil supplies. It in fact rallied to a five-week high in the Mumbai bullion market last week at Rs.13,185 per 10 gm on fresh support.
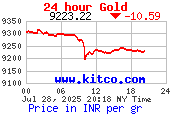
Apart from emerging as the safest asset, this is the peak “marriage” season in India and naturally, demand is fulled also to a large extent due to the season. Marriages are once-in-a-lifetime events, at least for the majority of the Indians. And unless the area is under curfew or there have been losses of lives in the family, marriages are usually not postponed. And if marriages have to happen in India, there is no way buying gold could be avoided. So irrespective of the terror attacks we thus see the prices of gold peaking. No wonder the foreign companies trying to set shop here go berserk trying to understand the psyche of the local people!
If you have money save it in gold,
"Gold is Gold bet"
With shining India Gold is and will continue to Shine.
Also gold jewelery comes with insurance package — Pantaloons ties up with ICICI Lombard
Here is investment Life cycle and observations about stock and gold.
- 1970s were great for gold, but terrible for stocks.
- The 1980s and 1990s were wonderful for stocks, but horrible for gold.
- As of 2008, this decade has been a good one for gold, and an unfavorable one for stocks.
bottom line is Gold is A Safest Investment Option and Excellent Hedge Against Inflation.
Recession is coming, How to act wisely during recession?
check out below common questions and my answers.
First and most important thing, make your own judgment, don't panic and pray!! Do what is wise.
Well what is Recession?
Recession:The state of the economy declines; a widespread decline in the GDP and Decline in the employment and trade lasting from six months to a year.
The recession looks very eminent. It is really time to take pro active steps to avoid a painful time in the next two years which is how long the recession is expected to last.
Checklist to fight in recession.
1. My suggestion on Loans; home loan, personal loan
DON'T TAKE ANY LOANS;
Don't BUY HOMES, PROPERTIES WITH LOANS,
Don't buy any/many things with CASH.
Act wisely KEEP AS MUCH CASH AS POSSIBLE.
2. What if I have personal loans?
During recession it is better to Pay off as much of personal loans, private loans, as debt collection will be hastened.
3. What to do with stock in Indian stock market?
Well its very hard to say; as if i say Sell any stocks you can even at lower prices; It will be against the warren buffet's policy; If you have enough cash; then put money in selective stocks, and don't look for short term returns during recession.
4. What to do with money in Trust Funds.
Take money off from Trust Funds.
5. What about market whispers?
Don't believe in huge sales forecast from customers, be extremely prudent, lowest inventories, reduce liabilities.
6. Can I invest in new capital?
Don't invest in new capital.
7. What to do with current homes?
Its million doller question most of us have invested in homes as a good investment option and with market boom. I had taken home in recent times, but If you are selling homes/ properties/ cars, do it now, when you can get good prices, they are going to fall.
8. Can I invest in new business?
Don't invest in new business proposals now. As recession is going to effect each and every segment of market, business goes if the money keeps rotating in market. Less money rotating less profits. One of my friend started business two years ago, now he is also affected with recession as money is not rotating in the market, there is less cash flow.
9. What about holiday plans?
Cancel holiday plans using credit cards.
10. Can I change job now?
Don't change jobs, as companies will retrench based on 'last in first out'.
Stay cool, wait, and if you took all of the above actions and more, you probably will be better off then many. This is not a rumor. Bear Stearns is the first of many banking and financial institutions that will start falling in the not too future. If Bear Stearns can fall, so can JP Morgan, Citibank, HSBC, and the whole world. US economy falls, the rest will crumble.
India and all those self economies will be the most protected, but not gullible.
Why Am I Having Financial Problems?
There can be two reasons for financial problems, and you must identify to which category you belong.
One category contains those who are having relationship problems. You could be well focused on your business, and putting your best efforts into it. You could be trying everything possible within your reach, but the financial issue isn't being resolved because of relationship problems.
There can be so much hurt and so many negative emotions in a relationship that it is manifesting as some form of financial or other external crisis.
If you fall in this category, then you can ask for Amma Bhagavan's grace to help you accept your relationship, to help you go through the pain of it and come out with love and joy. Once you are filled with love and joy, your external world will naturally become prosperous.
The second category of people are those who do not respect the external world, holding that the material world, or pursuit of the material, is some-thing inferior, and that it should be abhorred and not pursued. You may believe that it is anti-spiritual, that this is something that takes you away from enlightenment, or that this is not Oneness.
If you are a victim of these illusionary concepts, you are not going to draw wealth into your life. Because deep within you, you disrespect wealth, you disrespect prosperity, and you disrespect abundance. Somewhere deep within, you value and adore poverty as a symbol of spirituality or spiritual evolution. If this is the case, again, you are not going to draw wealth into your life.
You must become aware of these limiting ideas. Maybe because of some religious conditioning, or whatever, you believe that the internal and external world can never exist together, that you can have only one of them. For some reason you believe that you can have either an internal state or external prosperity. But this is not the case. No.
Amma and Bhagavan are Twin Avatars, and they want to unite both these aspects in human life. They want to bring about internal awakening as well as external prosperity. So if you can become aware of the limiting concepts that are within you, and if you pray that these concepts give way for external prosperity and abundance to come into your life, you will have it.
Here is a technique to get free PR7 Backlink .
Steps :
- Go to www.barcamp.org/BarCampDelhi
- Click on Edit Page
- Enter your Link and Save Page !
The password is c4mp .
Looking for more ? Here is a list of all pages . Many are PR6 and PR7 .
barcamp.org/BarCampNewsArchive
credit to earnpros
____________________________________________________________________
____________________________________________________________________
Hai Firefox fans, you just helped Mozilla set a unique Guinness World Record for the “Most downloaded software in 24 hours.
Though the official body of Guinness World Records is yet to approve this record attempt, Firefox is celebrating with certificates that also carry a Guinness World Records logo.
To print your own certificate, go to spreadfirefox.com, type your name and download the certificate in PDF format.
The thing is anyone can get this certificate ie you might not have taken part in downloading the firefox-3 still you can get this certificate. check out spreadfirefox.com
As I promised in my last post that will say my reviews on stocks, Today is the best time to talk about stocks as investment option being long term investor.
Why today is best day?
yesterday was this years first highest gain for Indian stock market and ie the trigger for second highest gain, which may happen today or tomorrow.
All blue chip stocks are trading at 20-25% less than their peak values.
One can except a good returns over next 18-20 months. please visit my views about investment and insurance in my previous post. Insurance and investment are different posted at My first blog
For example take SAIL - The present market capitalization of the company is close to Rs.80,000 cores at current market price of Rs.190 per share. The present debt of the company at Rs.2,500 cores makes company virtually debt free, net off, net current assets. Share is presently ruling at Rs.190, which discounts its FY 09 EPS by about 8 times. The steel sector is likely to remain attractive at the current levels, as all the stocks have corrected by about 30% to 35% in the last couple of months, which indicates 50% return in next 12 months. No one can bet on this.
Another example could be GMDC - Gujarat Mineral Development Corporation Ltd. (GMDC) is a Gujarat State government undertaking engaged in the business of lignite, bauxite and fluorspar mining as also power generation units based on Lignite, and market capitalization of close to Rs.5,000 cores for the company. The share which is now ruling at Rs.308, would go ex-bonus by the end of April at Rs.155. The stock at this rate is quite cheap, which can give a conservative return of close to 50% per annum over the next two years excellent bet on cum bonus basis.
These are just two example analysis and other include list I have mentioned above.
If you are long term investor like holding stocks for more than a year then you are exempted from capital gain tax. No need to pay tax after one year withdrawal, Think.
Before market opening .. Here we go..
enjoy./.
Bhagwat
Thanks for your response to my previous post,
Giving some simple rules of thumb for those who are serious about investment,
Investment is a long term goal, from where you understood the power of compounding and expects the returns from it.
One of the simple and best example of investment is land/plot, you must have observed the cost before two yrs down and now. Did you notice that in span of two yrs it valuations is double.
Fear- In this investment there is fear of, land/plot illegal acquire by other.
Then simple advice could be go for the land/plot purchase with reputed builder and make timely visit to your properties.
Why to purchase land/plot - As our experiences says from past ten years, nearly 20% people are living in cities, and in next 10 yrs, if indian growth story continues this figure will touch to 40% ie 40% people will live in cities, so just think and dont ignore my note. If you are serious investor and want good returns over your investment go for land/plot purchase near metro cities. Think for investment in tire-II and tire -III cities also.
As I tried to give you some notes in my previous post about ULIP plan, most of the ULIP provider says they give your minimum of 20% returns, just dont go by their words think that you can only get 10% max returns from it- this excludes their all charges.
So as an investor you have to play very smartly to get better rewards.
After all there is huge difference in horse riding and donkey riding, choose where your want to be.
Final words,
If you want great returns from your investment, invest in land/plot in and around metro cities, and see the magic. For insurance - golden suggestion is selection of right term insurance plan.
Keep reading, next post will be on stocks and insurance.
Todays post will be about auto insurance
The major difference between auto insurance risk and the life insurance is that, while you can only die once, you can have many auto accident claims. And the details can be far more varied, with losses for things like liability, medical payments and physical damage.
If you are involved in an auto accident or stopped by a police officer and found to be driving without car insurance or proof of financial responsibility, you will be subject to penalties specific to the laws of your state. For violation of the financial responsibility law, those penalties could include a fine or loss of driving privileges. If you are uninsured and in an accident that involves property damage or injuries to people, you will be required to pay out of-pocket for any damages assessed by a court.
well what is auto insurance?
Auto insurance is a contract with an insurance company that can protect you against severe financial loss if you are ever in an auto accident. Varying types of coverage act as a ?bumper? against various accident-related expenses, like liability, medical costs, damage to vehicles, and property damage.
Yes. After many years of rate increases, the cost of car insurance fell slightly in US, by 0.3%, in 1998, and another reduction is expected for 1999. The total reduction was estimated to be 2 or 3% after dividends on policies issued by mutual companies are considered -- like market leader State Farm. California, with 10% of the drivers, had a 5.7% reduction in cost last year. This decline came after reductions in each of the three previous years. High premium states like New York, Florida and Massachusetts are also seeing declines. Even New Jersey -- the state with the highest insurance costs -- is expected to get a 15% cut in 1999 because of a state mandate.
Factors that have contributed to the fall include:
1. The aging of the population
2. Safer cars (automatic seat belts and air bags)
3. Falling crime rates
4. Tougher drunk driving laws
5. Increased competition
Tougher competition is coming partly from companies that sell direct via telephone, direct-mail, and the Internet. They are contributing to the trend and gaining market share by offering lower costs. Companies that sell through agents still have 90% of the market but the direct sellers are growing faster.
There are many sites on the internet today that offer affordable car insurance free online quotes. All you have to do is a quick internet search, and literally millions of results will come up.
However, with all this competition today, it is becoming increasingly difficult to find the right company for you. Here are some tips to help you find the best firm for your affordable car insurance now.
First of all, you need to remember that some car insurance firms will give out discounts for various criteria. Each company has something a little different they look for, but here are the most prevalent: good driving records, your age, model of and amount of autos you currently have insured.
Depending on your own situation, you may be able to obtain a sizeable discount if you answer favorably to any of these questions. Also, you can often times get a cheaper rate for insuring your car with the same firm you have your home insurance policy with.
Of course, the bottom line price will come into play as well. Some companies are so much more expensive than others that, even with some discounts, you will still be paying more than you would be with another firm.
The most effective way to find an affordable car insurance policy is to shop around; simply, don’t wait until the day you want to start driving your new auto to look for insurance. This is a sure recipe for failure, as you will likely have to take the quickest insurance policy you can find, even if it isn’t the best one for you.
When you do shop around, always check on the internet at first for affordable car insurance free online quotes. Online, you can instantly obtain literally hundreds of insurance quotes at the click of a button, and it saves you a lot of time, versus having to pick up the phone and call each one individually.
Once you’ve found a good company, do a quick internet search and see what comes up about them. If you see a lot of complaints, then it’s best to find another firm. If, however, many people are saying positive things about them, then that’s certainly a good sign. Follow these tips, and you can find the best affordable car insurance with these free online quotes.
Auto insurance Glossary
For more auto insurance terms and tips, check out http://www.mycar-insurance-tips.com/ Whether you want a classic car insurance company or regular, you will find answers here.
For complete source
keep reading.
I am going to present my knowledge on Insurance,
this will cover, different types of insurance, some tips on how to select good insurance and tips on how much insurance individual needs.
To start with Insurance sector is divided into
Life & Term Life Insurance
Car Insurance or Auto Insurance
Health Insurance
Business Insurance
Home Insurance
In todays post I will jot down my notes on Life & Term Life Insurance
I will try to put this post more in question answer type.
What is life insurance?
Life insurance is a contract, often called a “policy”, between you and an insurance company to provide money to a person you designate, in the event that you die during the time the contract is in force. In essence, during your lifetime you pay money, known as the insurance “premium”, to the insurance company. It promises to pay money to the persons you name, the “beneficiaries”, at your death. Some types of life insurance also give the policy owner the right to “borrow” a portion of the “cash value” within a policy, or to receive an “accelerated death benefit” if you become terminally ill or require confinement in a long term care facility.
Why Buy Life Insurance?
Life insurance protects those who depend on your paycheck. If you die prematurely, life insurance provides your dependents with ongoing income to replace yours. Life insurance should be an integral part of your financial planning strategy. A general policy can be an important planning tool:
1. Income replacement
If you have dependents, consider what would happen to them if they no longer had your income to rely on. Proceeds from a life insurance policy can help remove financial strain on your family after your death. Your surviving spouse or domestic partner could also see a reduction in future or present retirement income, so life insurance can help close this gap.
2. Pay outstanding debts and long-term obligations
Life insurance spares your loved ones the burden of paying for burial costs, credit card debts and medical expenses not covered by health insurance. In addition, life insurance can be used to pay off the mortgage, supplement retirement savings and help pay college tuition.
3. Estate planning
The proceeds of a life insurance policy can be structured to pay estate taxes so that your heirs will not have to liquidate other assets.
4. Charitable contributions
If you have a favorite charity, you can designate some of the proceeds from your life insurance to go to this organization.
Life Insurance as Part of Your Long Term Financial Plan
You may not want to think about it, but your death can be financially devastating to the people you love. At the very least, there are funeral and burial costs which can run in the thousands. There may also be estate taxes and outstanding debts to pay. If you have dependents, they will have to cope with these costs while no longer having your income to rely on.
The proceeds from a life insurance policy can be of tremendous value. The "death benefit" will provide economic assistance to your family right when they need it the most. It's not just a money issue. Life insurance benefits will help your family maintain their current lifestyle with no interruptions while they deal with the emotional fallout of losing their loved one.
There are many choices when it comes to life insurance. More than 1,500 insurance companies offer policies, so it's important to work with a knowledgeable insurance agent to sort out the best policy for you.
Before you buy life insurance, it's important to know what options are available to you. Here's a quick overview.
Cash value life insurance comes in many shapes and sizes. The best known is "whole life," which covers you for your whole life with no change in annual premium as you get older. Others include universal life, variable life, single-premium life and adjustable life. Getting multiple life insurance quotes helps you identify which one is best for you.
Cash Value Insurance
Unlike term policies that offer the most protection for your premium dollar, cash value life policies have a savings feature. After you pay premiums for a year or so, cash accumulates. Even under most companies´ best-case scenarios, however, it takes years for the cash value to equal your premiums.
A few companies offer no-commission or low-commission policies that build cash values more rapidly. These companies are a good place to get a quote to use for comparison as you shop. As you call around, ask companies for their guaranteed projections of a policy´s cash value after five, 10 and 15 years. Get multiple life insurance quotes before making a decision.
You can borrow against your cash value or draw it out by surrendering your policy (subject to a "surrender charge"). This "savings" feature and first-year commissions of up to 100 percent of premiums often make cash value life much costlier than a term life policy paying the same amount if you die.
Is Cash Value for You?
Is cash value life insurance ever a good buy? Occasionally. Some middle-aged people convert term policies to whole life to beat ever-rising premiums or (in the case of level term) to avoid non-renewal for health reasons. Cash value life also may offer tax advantages.
Before buying cash value life, hire a fee-only financial planner or tax adviser to review your options. Be aware that advisers who get insurance commissions have a financial incentive to sell you cash value life rather than term life.
If you decide to use a commissioned insurance agent, look for one with a "CLU" (Chartered Life Underwriter) designation. CLUs are well trained and must abide by high professional standards and a code of ethics. Cash value policies are so complex that even experts need pages of calculations to figure them out. It is wise, therefore, to avoid cash value life without expert advice.
Cash value life is so profitable for insurance companies and agents that consumers must watch out for unfair sales practices. Careful shopping pays when buying all kinds of insurance. Nowhere is this more true than when the product is cash value life.
Term insurance
Term life insurance is insurance that lasts for a specific time, such as 5 years or 10 years. The policy pays a death benefit in the event the insured dies during the specified period. Since term insurance is for a limited period and accumulates no cash value, the rates tend to be low for a given amount of insurance.
How much insurance will I need?
A simple straightforward reply would be 6 times of your annual income. Firstly if you're young your needs would be different from that of a middle aged individual.
Must choose the right company
Are you pondering over whether you should stick to LIC or trust one of those private insurers?
With our insurance regulator the Insurance Regulatory Development Authority setting stringent norms for insurance companies there's little reason to worry about your hard earned money.
and do some homework based on below facts.
• Promoters background
• Reputation of the Insurance company
• Track record of the company in settling claims
• Brand value: How strong is the brand value
After all - LIC is always there.. but be open and review to invest your hard earn money.
How to go ahead
If you know of a trusted insurance representative, you could start by reviewing your life insurance needs and existing coverage with that agent. Otherwise you might want to find an agent or insurance broker to work with you.
If you are person who prefers to do your own research, you can find plenty of insurance information and quotes on the Internet, or from direct marketing ads in magazines, newspapers,or in this My first blog etc.
It is in your own best interests to review and compare various offerings and prices.
Keep in mind that there are many insurance companies and they have different ways of selling their life insurance policies. Some may refer you to an agent representing their company while others will require you to fill-out a questionnaire before providing a quote or cost estimate.
You should pursue the approach and the specific offering that you are most comfortable with, and that works best for you.
And finally
visit different insurance providers
Give the data to insurance adviser,
Like your age, how many yrs you want to pay premium and how much insurance you need. Give these inputs to all insurance providers compare the results based on how much premium you need to pay and other benefits.
final advice..
Dont select the insurance plan based on, your friend suggested, your uncle suggested or Insurance agent is your close relative. dont go by others word to invest your hard earn money.
These days ULIP is capturing market, as most of our friends became ULIP agent(ULIP companies pays big commissions),
I am not Insurance advisor nor gogint to say about specific ULIP.
Whatever plan you are going to select be ensure to ask question on
what are initial charges, and what are charges after 3 yrs. ie withdrawal charges and if want to continue what are AMC charges.
For a long term investor it is very important to know the AMC charges. most of ULIP charge 2%, do some market study you can get best of it.
Most of insurance advisor suggest about, some ULIP plan and a term plan. Again a mixed of insurance and investment.
This year I have done investment in mutual funds(ELSS)+ Term plan(from SBI- life shealth). But in MF also AMC charges are huge.
compare the ULIP with MF+ term plan on long term investment view, ULIP beats MF+term plan combination. In ULIP the trick is one has to know when to swtich between the options provided by the ULIP provider. If you are going for ULIP, take the ULIP from agent who also assists in timely swtich between plans(one more point for comparasion, check out the switch charges also).
After all its our hard earn money ...
And all the best in choosing the right insurance..
Keep on reading..my next post will be on Auto Insurance...
enjoy reading..and put your comments/questions down.


 Posts


